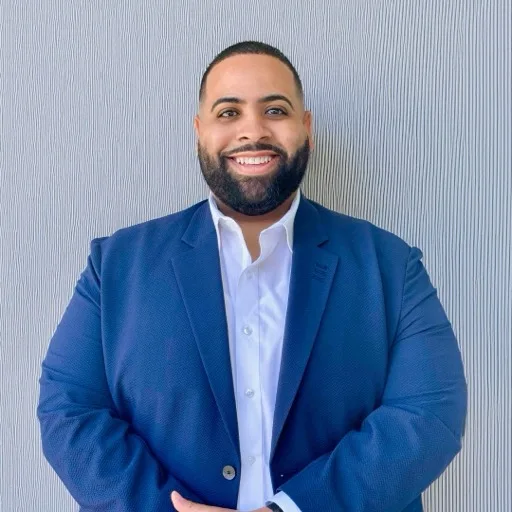
Ramon Liriano Jr.
Co-founder and Managing Partner at Elevated Tax Strategies. The front-of-house at the firm: Discovery calls, client engagement, operations, the bookkeeping team, sales, marketing, brand, partnerships. If you've talked to ETS, you've probably talked to me.
The front-of-house. Six lanes.
- Client engagement. Every Discovery call. Every engagement intake. The relationship with every client from day one through every quarterly check-in.
- Operations + SOPs. How the firm actually runs: Basecamp workflow, monthly close discipline, intake mapping, Round N preparer review handoff, tech-stack integration.
- The bookkeeping team. Hiring, training, quality control, and the working relationship with Kick. Our bookkeeping practice is the foundation everything else runs on.
- Sales + marketing. The Tax Discovery → Tax Analysis → engagement pipeline. The website voice. The content engine. The Hormozi-direct mechanics behind every page.
- Brand + content. Articles, scripts, deliverables, design system. If it has the ETS name on it, it goes through my hands.
- Partnerships. Kick, Relay, Bluevine, Gusto, Ramp: the tech stack relationships. The partners on /partners. The criteria for new ones.
Two-partner role split. I run the front. My partner runs the back.
ETS has two partners. I run the front-of-house (everything client-facing, operational, marketing-driven. Joel Salas, my partner, runs the tax practice itself) every tax position, every Round N preparer review on every return, every IRS representation matter, every advisory tax decision.
The split is what makes the firm work. When you book Discovery, I'm the one on the call. When you engage, Joel is the one signing your return + standing behind the tax positions. Neither of us delegates our half to associates. That's the entire pitch of the firm, you get the partners, not the associates.
The short version.
Husband. Dad. San Antonio resident. Read more about operations and how good teams actually work than about tax law (I leave that to Joel). Built ETS to be the firm I would have wanted to call when I was on the other side of the table.
Long version is in the articles below, and in the From the Operator Seat category specifically. I write that lane in first person about how the firm actually operates.
6 articles from me
Most-recent published first. I write across all seven Resources categories: though I'm most active in From the Operator Seat (operations, brand, firm philosophy) and the operational lanes (Tax Planning, Bookkeeping, Operating a Business).
-
The $500 HealthCare.gov Refund: Who Gets It, Is It Taxed?
Close to 1 million people who buy health insurance on HealthCare.gov are getting a one-time $500 refund from the U.S. Treasury. Here is who gets it, how it shows up, what we know about taxes, and how to tell a real payment from a scam.
-
Amending a Business Return: What It Costs and What It Touches
Owners ask what it costs to amend a business return and the honest answer is that the form is the cheap part. A change at the entity flows to every K-1 and then to every owner's personal return, and for most partnerships an amended return is not even the correct filing. Here is what actually gets touched.
-
The Year-End Handoff: Books Your Preparer Can Actually Use
The gap between books that look finished and books a preparer can file from is wider than most owners expect, and it is almost never the Profit and Loss. Here is what actually gets asked for in January, what to reconcile before you send anything, and the handful of questions that cause most of the back-and-forth.
-
Reconciling an Amazon 1099-K to Your Books
An Amazon seller's 1099-K almost never matches the deposits in the bank, and almost never matches revenue in the books. Neither is wrong. Fees, refunds, reserves and the calendar boundary each account for part of the gap. Here is the reconciliation that turns settlement reports into a defensible set of books.
-
Rental Renovations: Repair or Capital Improvement?
Owners often spend heavily on a property before ordering a cost segregation study, assuming every dollar becomes depreciable basis. The tangible property regulations decide it instead, using three tests and a unit-of-property rule that a cost seg can itself change. Here is the order to think in.
-
Can You 1031 Exchange a Primary Residence?
A home used purely as a residence cannot be exchanged under Section 1031. The useful question is different: when part of a property was business or rental use, Rev. Proc. 2005-14 lets you take the Section 121 exclusion AND defer the rest under 1031, in a specific order, with a five-year trap on the other end.
The Discovery call is where I do my best work. 20 minutes. Real conversation.
If you're considering engaging ETS (or just want to know if we're the right fit for your situation) book a 20-min Discovery. I run every one personally.
Book a free call →